The Golden Rule Every Grieving Family Must Know Right Now
The debts of the person who died are not your personal debts. Unless you co-signed on a specific loan or reside in one of nine community property states, you are not personally responsible for paying their credit cards, hospital bills, or personal loans out of your own pocket. Do not let aggressive callers convince you otherwise.
In the first few days after a loss, your mind is on the funeral. You are picking out a casket, ordering flowers, and trying to write a eulogy through the tears. For immediate guidance on the first 48 hours, see our Immediate Action Checklist After a Loss.
Behind the scenes, a very different storm begins to brew. Bills start landing in the mailbox. The phone rings with pushy callers demanding money. Scammers scan the online obituaries looking for vulnerable families to cheat.
This guide gives you a battle-tested playbook for the financial side of loss. You will learn how to safeguard your home and savings, how to shut down harassing collection calls, how to spot modern frauds, and when to bring in an experienced probate attorney.
Take a deep breath. Bookmark this page. Share it with your siblings or the appointed executor. Let us protect your family.
📑 Table of Contents
1. Protecting Your Personal Money and House
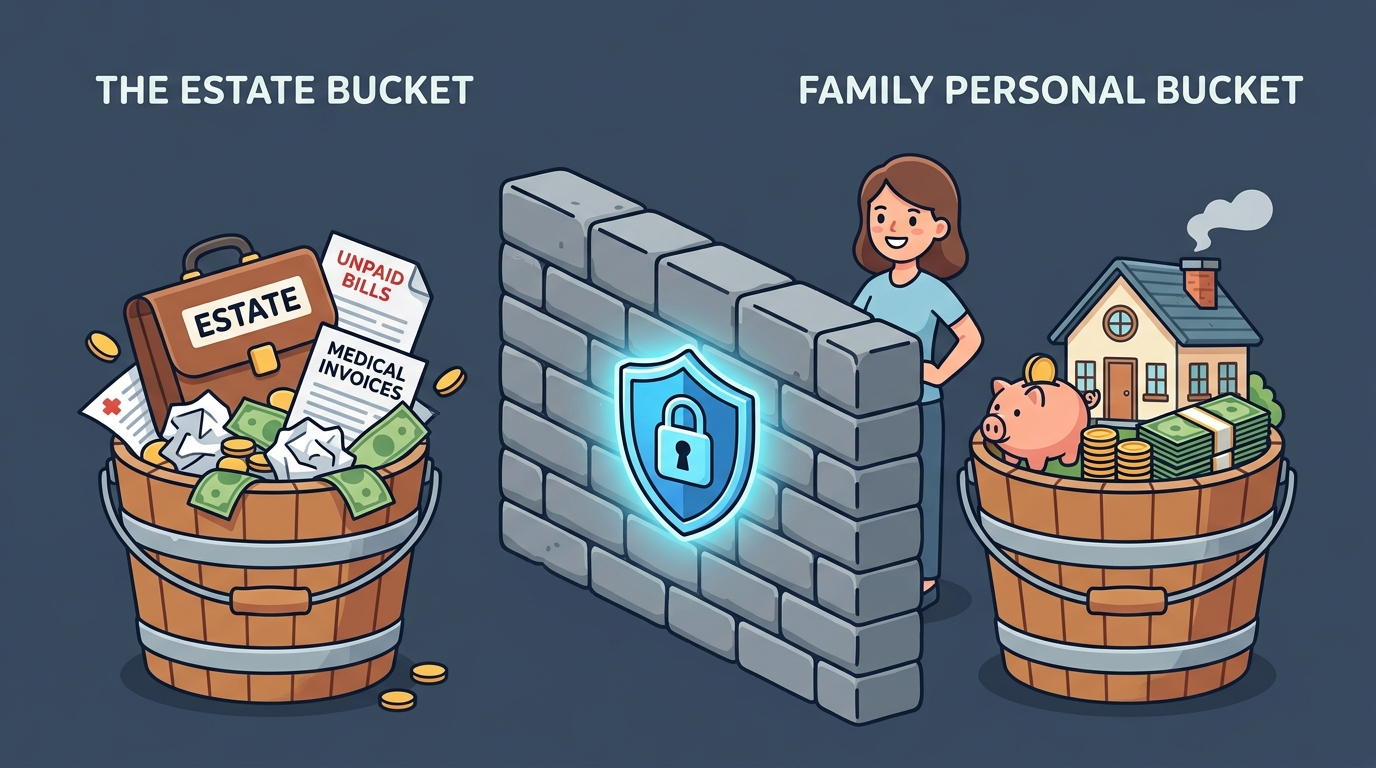
When someone passes away, their money and property become a distinct legal entity known as the Estate. Think of the Estate like a standalone bucket. That bucket holds everything the deceased individual owned at the time of death, and it is the sole job of that bucket to satisfy valid claims.
Your personal checking account, your retirement plan, and your family home sit in an entirely separate bucket. Creditors cannot reach their hands across into your bucket to satisfy the deceased person's debts.
Several specific legal mechanics make this personal protection rock solid:
✓ Joint Bank Accounts and Shared Property
If you owned real estate, vehicles, or bank accounts as joint tenants with rights of survivorship, ownership transferred 100 percent to you the second the person passed. The asset bypasses the probate estate entirely. Unsecured credit card issuers and medical collection agencies have zero claim on it.
✓ Payable on Death (POD) and Transfer on Death (TOD) Accounts
Many accounts include a designated beneficiary. These are called Payable on Death or Transfer on Death registrations. When you are listed as the designated beneficiary, the balance transfers straight to you upon showing a death certificate. It never enters the probate bucket. For details on how many certificates to order for each institution, read our guide on How Many Death Certificates Do You Need?
✓ Life Insurance Policies and 401(k) Accounts
When an insurance policy or retirement account lists an individual by name, that payout belongs exclusively to the beneficiary. Creditors cannot seize it. The single danger occurs when someone mistakenly writes "The Estate of [Name]" as the beneficiary. If that happens, the funds land in the creditor pool. Learn more about beneficiary designations in our breakdown of Burial Insurance vs Life Insurance.
✓ The Primary Residence Homestead Exemption
Families frequently fear that a credit card company will force a foreclosure on the family home. In the overwhelming majority of states, homestead statutes shelter a primary residence from unsecured judgment creditors. In states like Florida, Texas, and Iowa, homestead protection is virtually unlimited. Surviving spouses are legally entitled to continue living in the residence without forced creditor sales.
⚠️ The Major Exception: State Medicaid Estate Recovery (MERP)
If the deceased was 55 or older and received state Medicaid assistance for long-term nursing home care, federal law mandates that state Medicaid agencies attempt to recover costs from the remaining probate estate. If a surviving spouse or a permanently disabled child resides in the home, the state cannot force a sale. However, navigating Medicaid recovery requires specialized elder law counsel. If your loved one received Medicaid nursing benefits, consult a qualified attorney before signing any probate forms.
2. What to Say When Debt Collectors Call
This is the most stressful hurdle for families. You are trying to heal, and the telephone rings. An aggressive representative claims you must pay your late parent's $15,000 credit card balance immediately, threatening legal action or ruined credit scores.
Stay calm. Keep your credit cards in your wallet. Do not agree to send a penny.
Unless your signature appears as a co-signer on that specific account, you owe exactly zero dollars. It does not matter how loud they get or how many times they call. The obligation belongs solely to the Estate. Even as an executor, your duty is to steward estate funds, never your own.
Your Federal Legal Shield
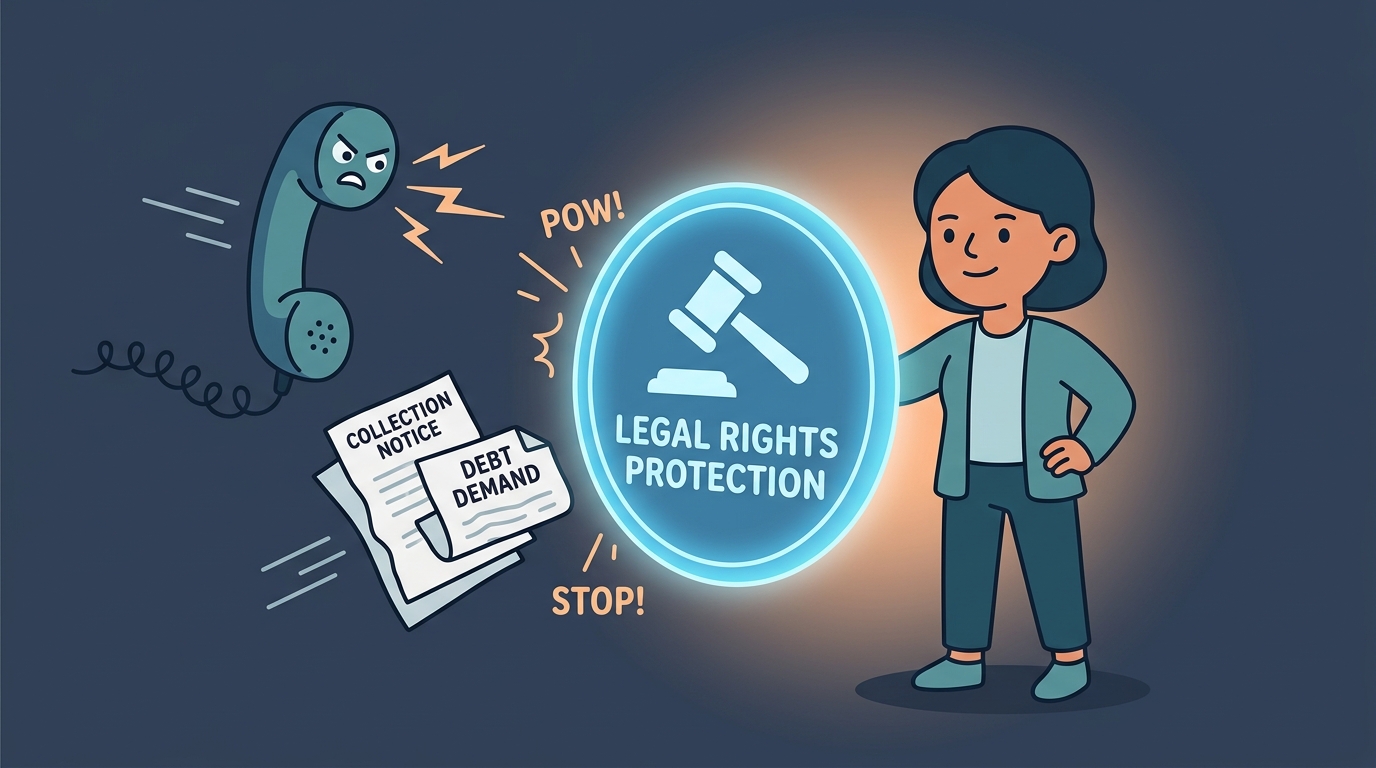
The federal Fair Debt Collection Practices Act (FDCPA) makes it illegal for collection agencies to harass, threaten, deceive, or call you during unreasonable hours. Crucially, it gives you the absolute legal right to demand they cease all phone communications.
The Non-Executor Stop Script
The Executor Formal Demand Script
🛑 The Dangerous Token Payment Trap
Collectors routinely use psychological manipulation: "If you just pay fifty dollars right now, we can hold off reporting this to credit bureaus." Never send a personal payment. Under contract law in many states, paying even twenty dollars from your personal bank account can be construed as a voluntary assumption of the debt. It resets expired statutes of limitations and exposes your personal accounts. Keep estate business entirely separate from personal funds.
3. Common Scams That Target Grieving Families
Scam operators read local obituary registries daily. They understand you are emotionally exhausted, sleep-deprived, and vulnerable. Here are the four primary frauds active today and how to shut them down.
Bogus Government Filing Fees
An official-looking letter arrives claiming an overdue $395 Estate Registry Fee or an $89 Death Certificate Archive Fee, complete with realistic barcodes and payment QR codes.
Number Suspension Phishing
A caller poses as a federal agent from the Social Security Administration, claiming the deceased person's number is being suspended due to fraudulent activity and demanding immediate identity verification.
Ghosting Fraud & Fake Tax Returns
Criminals harvest names and dates from obituaries, then file fraudulent tax returns to steal refunds or apply for retail credit lines before bureaus update records.
Threats to Cut Off Water or Power
A scammer rings claiming the decedent's electricity or heat will be turned off within sixty minutes unless you settle an outstanding emergency deposit using prepaid gift cards, Zelle, or Venmo.
🛡️ Deceased Credit Lock Checklist: Do This Within 14 Days
- Contact Experian, Equifax, and TransUnion: Submit a request for a Deceased Alert or Deceased Freeze on their credit file. Provide a copy of the death certificate once received.
- Request an IRS Identity Protection PIN: When preparing the decedent's final return, request an IP PIN from the Internal Revenue Service to block fraudulent filings.
- Review the Deceased Do Not Contact List: Register the loved one's details on the Direct Marketing Association DMAchoice registry to dramatically reduce unsolicited promotional mail and predatory pitches.
4. Special Rules for Spouses in Certain States
In 41 states across America, the traditional common-law framework protects spouses from debts taken out solely in the other partner's name. However, if you reside in one of nine specific jurisdictions, different rules apply.
The Nine Community Property States
In these states, property and debt accumulated during marriage are generally viewed as joint community property:
If you live in one of these nine states, debts incurred by either spouse during marriage can sometimes be collected from community assets, even if only one spouse signed the agreement. It is essential to consult an estate planning attorney in your jurisdiction before disbursing funds or paying credit cards.
Filial Responsibility Statutes
Approximately thirty states maintain historical filial responsibility statutes on their books, most visibly utilized in Pennsylvania. Under rare circumstances, health care facilities have attempted to sue solvent adult children for unpaid long-term nursing home care.
Federal law prohibits nursing facilities from pursuing adult children if the parent qualified for Medicaid coverage. If you receive an unexpected collection letter citing filial duty, do not make an unprompted payment. Forward the letter to an elder law attorney right away.
5. Which Bills to Pay First and Which to Ignore
If you are the executor or personal representative, you are tasked with paying legitimate claims against the estate. You do not pay them in the order they arrive in the mailbox, and you do not pay them equally. State law establishes a strict statutory hierarchy known as the Payment Waterfall.
Money flows downward from Tier 1 to Tier 6. If the estate runs out of money at Tier 4, the creditors in Tier 5 receive zero dollars, and their claims are legally wiped out.
| Priority Tier | Category of Expense | Required Executor Action |
|---|---|---|
| Tier 1: Super Priority | Funeral and Burial Costs | Pay this first. In all fifty states, reasonable funeral expenses hold statutory top priority over other creditors. The funeral home is paid before any credit card or hospital claim. For transparent pricing breakdowns, see our guide on Understanding Funeral Costs. |
| Tier 2: Secured Property | Mortgages and Vehicle Loans | Maintain payments if the family or heirs intend to keep the home or vehicle. If not keeping the asset, coordinate surrender with the lender. |
| Tier 3: Administration | Probate Fees and Attorney Costs | Court filing costs, fiduciary bonding, probate accounting fees, and executor compensation are paid directly from estate funds. |
| Tier 4: Government Claims | Federal and State Taxes | Settle final income taxes with the IRS and state department of revenue. Tax claims hold statutory priority over commercial debts. |
| Tier 5: Unsecured Debt | Credit Cards, Personal Loans, Medical Bills | Do not rush to pay these. Ignore phone demands until formal written claims are lodged within the statutory creditor window. Settle only if surplus cash remains. |
| Tier 6: Heirs | Inheritance Distributions to Family | Assets are distributed to named heirs according to the will or state intestacy laws once all higher tiers are satisfied and creditor windows have closed. |
What Happens When an Estate is Insolvent?
If the total unsecured claims in Tier 5 exceed the cash remaining in the estate bucket, the estate is deemed legally insolvent. When this occurs, credit card companies and collection agencies simply take a loss.
The family inherits zero debt, and family members are never required to chip in personal savings to make up the difference. Creditors write off the balance, the court closes the estate, and the family walks away clean.
6. The Executor 90 Day Action Plan
Serving as an executor sounds daunting, but breaking the responsibilities into chronological phases simplifies the entire process. Here is your roadmap for the first three months.
Immediate Asset Security and Documentation
- Secure the primary residence: change exterior locks if necessary and verify heating and security systems.
- Forward all physical postal mail to your address via USPS official forwarding.
- Order at least 15 certified copies of the death certificate through your funeral director.
- Notify the Social Security Administration so monthly benefit payments cease promptly.
Estate Account Setup and Inventory
- Apply for an Employer Identification Number (EIN) for the Estate on the official IRS website.
- Open an Estate Checking Account at a local bank using your Letters of Administration or Letters Testamentary.
- Consolidate solely owned cash into this new account. Never deposit estate checks into personal accounts.
- Compile a master inventory of real property, vehicles, bank accounts, and outstanding obligations.
Publish the Notice to Creditors
File a Notice to Creditors with the probate court and arrange for its publication in the designated local newspaper of record. This publication legally starts a creditor countdown clock (typically 3 to 4 months depending on state statute). If a creditor fails to submit a formal verified claim to the court before that window closes, their legal right to collect is extinguished permanently.
Claim Review and Priority Settlements
- Audit all written claims received through the probate court.
- Confirm whether credit card companies submitted valid documentation before the statutory deadline. Most high-volume card companies fail to file formal paperwork. If they missed the deadline, you do not pay them.
- Pay funeral expenses, property preservation costs, court filing fees, and tax liabilities using the priority waterfall.
Final Accounting and Heir Distribution
Prepare the final probate accounting for court approval. Distribute remaining balances to beneficiaries. Always obtain a signed Receipt and Release form from every heir before issuing checks to shield yourself from future liability.
7. How to Find and Hire the Right Lawyer
You are not an attorney, and you should not be forced to guess your way through state probate codes. If the estate contains real estate, complex investments, small business interests, or exceeds $50,000 in assets, retaining skilled counsel is one of the smartest investments an executor can make.
Which Type of Lawyer Do You Need?
Probate and Estate Administration Attorney
Specializes in probate court filings, creditor claim validation, estate tax clearance, and legal asset distribution. They step in between you and the collectors so you do not carry the stress.
Elder Law Attorney
Essential if the deceased individual received Medicaid long-term care or nursing facility subsidies. They know statutory hardship exemptions to protect the family home from state estate recovery.
Where to Find Vetted Specialists
- Ask Your Local Funeral Director: Funeral directors interact with probate lawyers every week. They know which attorneys treat families with empathy and reasonable rates, and which ones overbill.
- The ACTEC Directory: The American College of Trust and Estate Counsel (actec.org) provides a searchable directory of peer-reviewed trust and estate specialists with verified credentials.
- Your State Bar Association Referral Service: Every state bar operates an attorney referral service that verifies active licensing, clean disciplinary records, and required malpractice insurance.
- Ask the County Probate Court Clerk: While clerks cannot provide formal legal advice, they observe which local practitioners submit clean filings and manage cases smoothly.
❓ The 5 Essential Questions to Ask Before Hiring
Always insist on an hourly rate or a defined flat fee. Never agree to statutory percentage billing based on gross estate value, which can cost thousands more.
Familiarity with local judicial customs, clerk staff, and court scheduling saves weeks of administrative delays.
Clarify who your direct point of contact will be for day-to-day updates.
Once an attorney represents the estate, collectors are legally forbidden from calling you and must speak only to your lawyer.
Many experienced practitioners offer capped fee agreements for uncontested probate administration.
Red Flags When Interviewing Lawyers
Be cautious of any attorney who suggests skipping formal probate procedures entirely when titled real estate is involved, as this can cloud title ownership for years. Also steer clear of firms demanding a percentage of gross real estate values before any work begins.
Conclusion: Knowledge is Your Best Defense
Grief is painful enough on its own. Do not permit aggressive collection agencies or dishonest scammers to add financial anxiety to an already challenging chapter.
Keep These Three Rules in Your Mind at All Times:
- Your personal property is safe: Debts belong to the separate estate bucket, not to you or your home.
- You have the right to silence collection calls: Use the federal cease-and-desist scripts. Never make token personal payments.
- You do not have to fight alone: An experienced probate attorney costs a fraction of the thousands they save your family in improper claims.
Share this guide with your family members and the appointed executor. Keep a printed copy alongside the certified death certificates. The next time a debt collector calls, you will not respond with fear. You will respond with the quiet confidence of knowing exactly what the law says.
🔗 Helpful Resources on Our Site
Understanding Funeral Costs in 2026
Why funeral and burial bills hold statutory priority over all other creditors.
Death Certificates: The Essential Guide
Why you need 15 certified copies and exactly where each copy must be sent.
Burial vs Life Insurance
How beneficiary payouts bypass probate and remain protected from creditor claims.
Funeral Crowdfunding Campaign Setup
How to raise immediate community support while estate bank accounts are frozen.
Legal Disclaimer
This article is published for educational and consumer informational purposes only and does not constitute formal legal, accounting, or financial advice. Statutory probate regulations, homestead protections, and filial laws vary significantly across state jurisdictions and evolve over time. If you are administering an estate or facing aggressive debt collection actions, consult a licensed attorney in your state for personalized guidance on your specific legal circumstances.